

Nagad Uddokta

- 429.00 Reviews
- 4.2
- Downloads
- 5,000,000+
Our take on Nagad Uddokta from Appgk
When I look at a finance app, I care less about flashy design and more about whether it helps me complete routine work without confusion. Nagad Uddokta is built for that practical purpose. It is an app from Nagad Limited for Nagad Uddokta users, so its role is narrower than a general wallet or personal banking app. I would approach it as a working tool for people handling Nagad-related services, not as an application meant for every customer who simply wants to manage personal money.
That distinction matters from the first screen. The app’s store summary describes it as a channel app for Nagad Uddokta, which sets a different expectation from a consumer payment app. In my view, the strongest reason to consider it is this focused audience: if your daily responsibilities involve Nagad Uddokta activity, a dedicated channel app can be more useful than trying to adapt a general finance application to the same job.
Nagad Uddokta is free, carries an Everyone age rating, and belongs to the Finance category. It was released on April 28, 2020, and the current Android version is 1.0.119.01, with Android 5.0 or later required. Those details make it accessible to people using older Android phones, although the actual experience will still depend on the phone’s condition, available storage, network quality, and the account setup connected to the service.
Trust starts with knowing who this app is for
The developer is Nagad Limited, and the app has reached over five million installs with a 4.2 average from around thirty-five thousand ratings. I do not treat those figures as proof that every user will have a smooth experience, but they do show that this is not an obscure utility with a tiny audience. More importantly, the audience appears to be tied to a specific operational role rather than casual experimentation.
Best Parts of Nagad Uddokta
Things to Keep in Mind About Nagad Uddokta
For me, that role-based design is the first trust signal. A finance tool should make its purpose clear, and Nagad Uddokta does not present itself as a universal replacement for a bank account, a personal wallet, or a budgeting app. If I were deciding whether to install it, I would first ask a simple question: am I actually a Nagad Uddokta user who needs this channel? If the answer is no, installing it just because it is free would probably create more uncertainty than value.
This is also where the app differs from usual alternatives. A personal mobile wallet is generally designed around the individual customer’s balance, transfers, payments, and account history. A banking app usually focuses on the customer’s own accounts and financial products. Nagad Uddokta is better understood as a role-specific access point. Its usefulness comes from fitting that work context, not from offering a broad collection of personal finance tools.
News and Features Related to Nagad Uddokta

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
I would therefore judge it by different standards. I would want the sign-in and account flow to be understandable, the app to keep actions connected to the correct account, and the interface to make it obvious when I am performing a work-related transaction. I would also want to pause before confirming anything involving money, especially when I am serving another person. A focused app can reduce unnecessary steps, but it can also make a mistaken tap more consequential if I move too quickly.
What the public numbers tell me—and what they do not
The rating is useful as a starting point, not a guarantee. A 4.2 average suggests that many people find the app workable, while the presence of several hundred written reviews indicates that users have taken time to describe their experiences. Still, ratings combine different phones, networks, account situations, and expectations. Someone using the app as part of a busy outlet may judge it very differently from someone who opened it without understanding its intended audience.
Don't want to read the full review?
I would read the rating alongside the app’s narrow purpose. If I needed a personal finance dashboard, I would not choose this app simply because its score looks respectable. If I needed the Nagad Uddokta channel, the same score would be more relevant because the app is being judged in the environment it was designed to serve.
Account control deserves careful attention
Finance apps are different from ordinary social or entertainment apps because account access has practical consequences. With Nagad Uddokta, I would take extra care during sign-in, device changes, and any moment where the app asks me to confirm an action. I would use only my own account details, avoid sharing credentials, and keep the phone protected with a screen lock. Those are not exciting steps, but they are more important than cosmetic features when an app is connected to financial work.
Screenshots
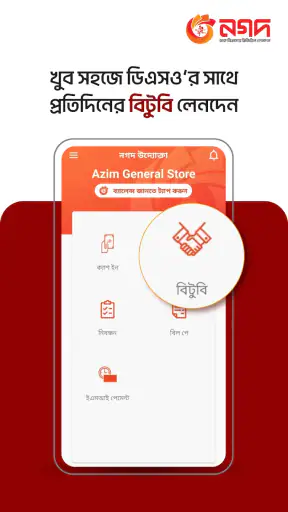
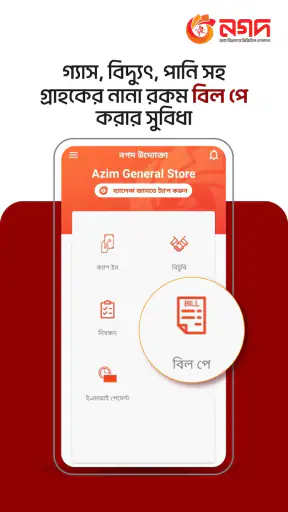
I would also avoid treating a successful login as proof that every later action is safe to approve automatically. My habit would be to check the account context, recipient or customer details, amount, and final confirmation screen before proceeding. This is especially important in a busy shop, where interruptions and queues can encourage rushed decisions.
One practical workflow I would recommend is separating “prepare” from “confirm.” First, collect the necessary details and review them. Then perform the final action only after checking the information again. That small pause is useful in any finance app, but it is particularly valuable in a channel application where one person may be helping many customers in succession.
How the app fits into real daily work
Imagine I am working at a small outlet during a busy afternoon. A customer arrives needing a Nagad-related service, and I need to use the channel app rather than my personal wallet. I would open the app, make sure I am using the correct account, enter the customer’s information carefully, and review the transaction before confirming. Afterward, I would keep the result clear to the customer instead of relying on memory or a rushed verbal explanation.
The important insight here is that the app should be treated as part of a wider routine, not as the whole routine. I would keep a simple method for matching each customer request with the action I am taking, particularly when several people are waiting. I would also avoid switching between unrelated apps while a transaction is in progress. Reducing distractions is a realistic way to lower the chance of entering information into the wrong screen or losing track of which customer I am serving.
Another useful habit is to check the connection before starting a time-sensitive action. A weak network can make any online finance workflow feel uncertain, especially if the screen takes time to respond. I would not repeatedly tap a confirmation button just because the first tap does not produce an immediate result. Instead, I would wait, inspect the screen, and verify the outcome before trying again. Repeating an action without checking can create confusion about whether it was processed once, twice, or not at all.
This is one of the app’s likely trade-offs as a dedicated channel tool: its value depends heavily on the surrounding work conditions. A reliable connection, a protected phone, and a careful operator can make the experience much more manageable. A shared device, constant interruptions, or unclear account ownership can make even a straightforward app feel risky.
Older Android support is helpful, but not a complete promise
Because the minimum requirement is Android 5.0, people with older devices may be able to install it instead of replacing a phone solely for this purpose. That is a practical advantage for small outlets where equipment budgets matter. At the same time, minimum compatibility does not mean every older device will feel equally responsive. Battery health, free storage, background activity, and the quality of the mobile connection can all affect day-to-day use.
If I were setting up the app on an older phone, I would keep the device dedicated to essential work where possible, remove unnecessary clutter, and make sure the operating system is maintained as far as the handset allows. I would also test the complete sign-in and transaction workflow before relying on it during a busy period. This is not a hidden feature; it is a sensible preparation step that prevents discovering a device problem when a customer is waiting.
Where trust needs a cautious approach
My trust in a finance app comes from visible choices and careful behavior, not from assuming that a familiar name removes all risk. With Nagad Uddokta, I would pay attention to what the app displays during account access and transaction confirmation. I would not grant access casually if the operating system presents a permission request that does not seem connected to the task, and I would review the phone’s app permissions periodically rather than approving everything automatically.
I would also think about the data-sensitive moments around the app. Entering a customer’s details, handling account information, viewing transaction results, and using the application in a public outlet all require discretion. I would position the screen so others cannot easily read it, avoid taking screenshots of sensitive pages, and clear paper notes or handwritten details after they are no longer needed. These choices protect the people involved even when the app itself is functioning normally.
Device sharing deserves special caution. If more than one person uses the same phone, I would want a clear process for signing out or locking access when the workday ends. I would not assume that closing the app is the same as ending an account session. Before handing the device to someone else, I would inspect the visible screen and make sure no customer information remains open.
These are important limitations of the overall setup rather than claims that the app is unsafe. A finance application can be used responsibly or carelessly, and the surrounding habits influence the outcome. My recommendation is to treat every displayed account or customer detail as private, even when the phone is being used in a familiar shop.
What I like about the focused design
The clearest strength is purpose. Nagad Uddokta is not trying to be a general-purpose money manager in my review of it. That can make it easier for the intended user to think in terms of work tasks instead of personal spending, budgeting, or unrelated financial features. A focused tool is often preferable when the job requires repeating a defined set of actions.
The free price also lowers the barrier to trying it, and the Everyone rating makes the intended audience broad in age terms. Still, I would not confuse broad age suitability with universal suitability. The application may be appropriate for a wide range of users who perform the relevant role, but it is not automatically the right choice for children, casual wallet users, or people looking for investment analysis and household budgeting.
I also appreciate that the app can be considered on older Android hardware. In real life, a small business may already have a working phone and may not want to purchase a new device for every software update. Compatibility with Android 5.0 or later gives that kind of user more flexibility, provided the device can handle the workflow reliably.
A less obvious advantage is that a dedicated work identity can help prevent accidental mixing with personal finances. If I use a personal wallet for both my own transactions and customer assistance, it becomes easier to lose track of which action belongs to which purpose. A role-specific app creates a clearer mental boundary. That boundary is not a substitute for careful records, but it is useful operationally.
Where I would choose something else
I would skip Nagad Uddokta if I simply wanted to send money, pay bills, monitor personal spending, or manage a conventional bank account. A consumer wallet or banking app would be a more natural fit because those products are organized around the individual account holder’s needs. Installing a channel app without the corresponding role would not give me a better personal finance experience.
I would also hesitate if I needed a detailed budgeting system, financial charts, investment tools, or broad account aggregation. The app’s identity is tied to Nagad Uddokta activity, so I would not expect it to replace specialist tools designed for planning or analysis. Choosing the right category matters more than choosing the highest-rated application.
Another reason to pause is operational pressure. If my outlet has unstable connectivity, an unprotected shared phone, or several people using one account, I would fix those conditions before depending on the app. The application may be suitable, but the environment could still make transactions difficult to verify. In that situation, a clearer device policy and backup procedure would be just as important as the installation itself.
My verdict for prospective users
After considering its audience, access needs, and practical use, I see Nagad Uddokta as a specialized finance app rather than a general recommendation for everyone. Its strongest case is straightforward: a Nagad Uddokta user needs a dedicated Android channel for work and wants a free app that supports older versions of the operating system. For that person, the focused purpose and established user base make it worth considering.
My recommendation comes with a deliberate condition: use it with disciplined account and data habits. Check the account before acting, review every important detail before confirming, avoid repeated taps when the connection is slow, and keep customer information away from public view. Those steps turn the app from something I merely install into something I can use responsibly.
The rating and install reach give me reasonable confidence that the app is being used at scale, but they do not remove the need for personal judgment. Finance software should never be trusted blindly, and a channel app should not be mistaken for a personal wallet. I would choose Nagad Uddokta when my work specifically calls for the Nagad Uddokta channel; otherwise, I would select a consumer finance app that matches my actual needs more closely.
My cautious verdict is that Nagad Uddokta is a sensible, role-specific choice for the people it is intended to serve. It earns consideration through clarity of purpose, free access, broad Android compatibility, and a substantial user presence. It is not the right tool for personal budgeting or ordinary wallet use, and its safe operation depends on careful handling of accounts, devices, and customer details. If that matches your situation, I would give it a try after preparing the phone and workflow properly.
Nagad Uddokta FAQ
What is Nagad Uddokta used for?
Nagad Uddokta is designed for authorized Nagad agents, commonly called Uddoktas, who provide mobile financial services to customers in Bangladesh. Through the platform, agents may help users cash in, cash out, send money, pay bills, and complete other supported transactions. It is not generally intended to function as a regular personal wallet for customers, so access and available features depend on agent authorization.
Who can use the Nagad Uddokta app?
The app is primarily intended for registered Nagad Uddoktas and authorized merchant or agent points. During setup, users may need approved credentials, a registered mobile number, and account verification information supplied by Nagad. Ordinary customers should normally use the standard Nagad consumer application instead. If you are unsure whether your account is eligible, contact official Nagad support before downloading or attempting to sign in.
Is Nagad Uddokta safe for handling transactions?
Nagad Uddokta includes account access and transaction-related functions, so users should treat it as a sensitive financial application. Download it only from an official store or Nagad-approved source, keep the app updated, and never share PINs, passwords, one-time codes, or verification details. Always confirm customer information and transaction amounts before approval, and report suspicious activity through official Nagad support channels.
What services and transactions are available in Nagad Uddokta?
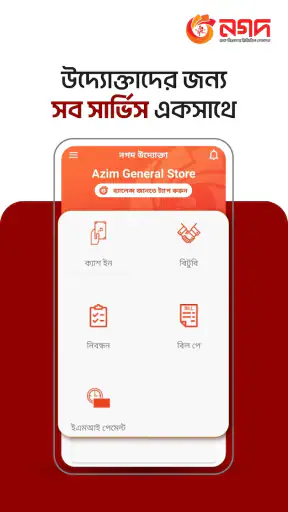
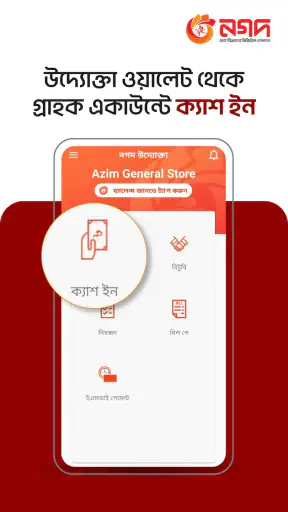
The exact services can vary according to the agent’s account type, location, permissions, and current Nagad policies. Common functions may include customer cash-in and cash-out, money transfer assistance, mobile recharge, bill payment, balance or transaction checking, and viewing service records. Availability, limits, fees, and required verification can change, so users should review the displayed terms and confirm charges before completing a transaction.
What should I do if Nagad Uddokta does not work or I cannot log in?
First, check your internet connection, confirm that you are using the registered mobile number and correct credentials, and update the application if a newer version is available. Avoid repeatedly entering incorrect security details, as this may trigger account restrictions. If the problem continues, contact Nagad through its official customer-care channels or your assigned representative. Do not rely on unofficial websites, social-media messages, or third parties requesting account information.











